On October 29, Eli Lilly delivered a quarterly result that makes the obesity-drug market look less like a promising category and more like an economic system of its own. Mounjaro generated $10.723 billion in worldwide third-quarter sales, while Zepbound brought in $5.352 billion. Together, the two tirzepatide brands accounted for more than $16 billion in three months.
That is the eye-catching number. The more revealing detail is that Lilly’s company-wide sales volume rose even faster than revenue, while realized prices declined.
Volume Is Growing Faster Than Revenue
Lilly reported total third-quarter revenue of $24.397 billion, up 39% from a year earlier. Across its worldwide business, the company attributed that performance to a 53% increase in volume, partially offset by a 15% reduction in realized prices.
The arithmetic matters. It means considerably more medicines moved through Lilly’s commercial system, but changes in realized pricing offset part of the volume-driven revenue increase.
That is not necessarily evidence of a simpler or cheaper patient experience. Realized price reflects a complicated mix of discounts, rebates, geography, product mix and accounting adjustments.
The percentages also apply to Lilly’s overall business, not exclusively to tirzepatide. The company reported different price and volume movements across markets and individual medicines.
Mounjaro and Zepbound Are Not One Market
Worldwide Mounjaro revenue grew 65% to $10.723 billion, and Zepbound grew 49% to $5.352 billion.
Mounjaro’s expansion outside the United States was especially pronounced: Lilly said international revenue reached approximately $5.7 billion, up 93%, with growth partly offset by lower realized prices after the drug joined China’s National Reimbursement Drug List in the first quarter of 2026.
Zepbound’s U.S. revenue climbed 48% to approximately $5.3 billion. These are different commercial channels and indications, even though both products contain tirzepatide.
The distinction matters when interpreting the combined revenue figure. The two brands participate in overlapping but different markets shaped by diabetes treatment, obesity care, international reimbursement policies and insurance coverage.
A Lower Net Price Is Not a Cheaper Prescription
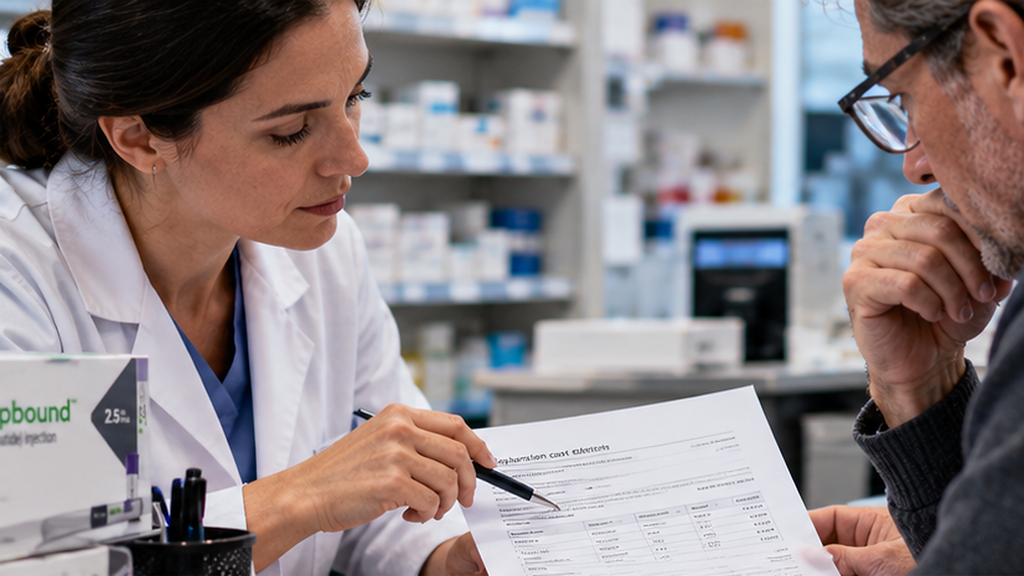
The distinction between prescription volume, net manufacturer revenue and the amount a person pays at a pharmacy is central to understanding this market.
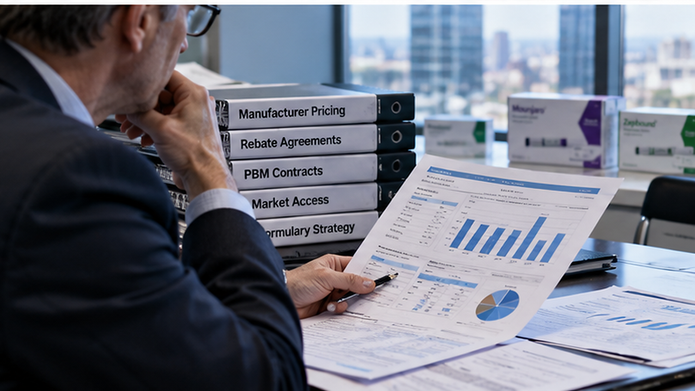
A patient may see a cash-pay offer, an insurer may negotiate a rebate, a pharmacy benefit manager may administer a formulary, and the manufacturer may ultimately recognize a different net price.
These amounts do not necessarily move together. A decline in manufacturer realized prices can coexist with high out-of-pocket costs for patients, depending on their coverage and circumstances.
When a headline declares that drug prices have fallen, the next question should be: which price, paid by whom, and over what period?
The Oral Launch and the Accounting Beneath the Headline
The quarter also illustrates why a successful injection does not guarantee a triumphant pill launch.
Lilly reported $184 million in third-quarter sales for Foundayo, its oral obesity medicine, a much smaller contribution than the established injectable brands.
That is a launch snapshot, not a definitive verdict on the product. Oral dosing may broaden choice, but demand will depend on coverage, comparative evidence, tolerability, adherence and competition.
The company is building multiple routes into the broad metabolic-treatment market rather than simply replacing one route with another.
Lilly’s earnings release also identified approximately $900 million in quarterly revenue benefits from several items, including $410 million of Jardiance milestones and favorable rebate and discount estimate adjustments.
Those items matter when interpreting the headline revenue and earnings. Reported earnings per share were $7.22, while non-GAAP earnings per share were $7.48; both included sizable acquired research-and-development charges.
The earnings result is substantial, but not every dollar of reported revenue reflects a straightforward new prescription filled at a retail counter.
A $92 Billion Forecast Meets the Coverage Question
The company raised its full-year revenue outlook to $91 billion to $92 billion.
That guidance reflects confidence in its operating momentum, not a guarantee that demand, policy or competitors will cooperate.
The broader obesity sector is entering a period in which manufacturers must simultaneously finance expensive trials, expand manufacturing, negotiate access and explain why their products deserve a place in increasingly crowded treatment pathways.
Commercial scale creates leverage, but it also increases scrutiny.
For payers, the numbers create an uncomfortable question: how much budget should be allocated to treatments that may require sustained use, and what health gains will justify the expense?
For patients, the more immediate issue is continuity. A medicine that works biologically can still fail practically if a plan changes its formulary or an out-of-pocket price becomes unsustainable.
Lilly’s quarter measures commercial adoption, not the long-term persistence of every individual receiving treatment.
The Commercial Test for Every Rival
The numbers also demand discipline from competitors.
A new molecule cannot win by posting a dramatic weight-loss percentage alone. It must demonstrate meaningful benefit, acceptable safety, dependable supply and a credible route to reimbursement.
Lilly’s advantage is not simply a receptor profile; it is a large and growing combination of clinical data, production capacity, prescriber familiarity and payer relationships.
That is why a smaller rival’s promising Phase 2 graph is only the beginning of the commercial story.
This is actual October 29 financial news, sourced to Lilly’s own third-quarter report. It should not be confused with the separate retatrutide trial headlines or presented as proof that treatment has become universally affordable.
The industry’s defining paradox is now visible in the same filing: extraordinary company-wide volume growth alongside declining realized prices.
The next chapter will be written not only in laboratories but in contracts, benefits designs and the ordinary question patients ask at the pharmacy counter: can I keep taking this?